
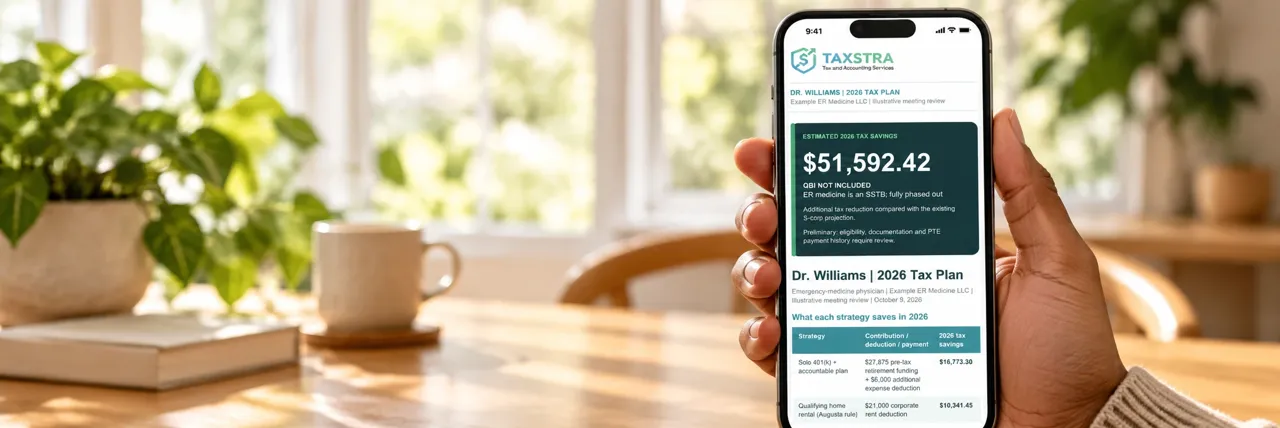
 Tax planningA year-round plan, built before decisions are made.Preview
Tax planning & accounting. Beyond tax season.
Modern tools and personal support for tax preparation, planning, and accounting. Built to help you keep more of what you earn.
Tax planning slots are limited before year-end.
Featured in

5.0113 Google reviews
1,000+clients served
nationwide
Find your next move.
Choose a topic. Select a photo card to preview it above.
What we do
- Tax planningA year-round plan, built before decisions are made.Preview
 Tax preparationFederal and state returns, prepared and explained.Preview
 BookkeepingMonthly books and statements you can actually use.Preview
 Entity & S corp setupChoose and set up the right structure for how you earn.Preview
 Fractional CFOPart-time CFO help with forecasts and big decisions.Preview
 PayrollPayroll and payroll filings, handled on schedule.Preview
 Multi-state filingEvery state return when you earn in more than one.Preview
 Cost segregationEngineering studies coordinated with our partner.Preview
Before year-end
Explore all Tax-Loss HarvestingUsing investment losses to balance out gains.Preview
 Roth ConversionsMoving savings to Roth in the right years.Preview
 Deduction BunchingTiming deductions so more of them count.Preview
 Cost SegregationSpeeding up depreciation on property you own.Preview
 Hiring Your ChildrenPaying your children for real work in your business.Preview
 Mega Backdoor RothExtra Roth savings when your 401(k) plan allows it.Preview
 Estimated taxesQuarterly payments planned so April has no surprises.Preview
 Cash Balance PlanA larger retirement plan for high-earning owners.Preview
For business owners
Explore all Entity StructureChoosing how your business is set up and taxed.Preview
 Accountable PlanReimbursing business costs you pay personally.Preview
- Hiring Your ChildrenPaying your children for real work in your business.Preview
 Augusta RuleRenting your home to your business for meetings.Preview
 R&D Tax CreditA credit for qualifying research and development work.Preview
- Estimated taxesQuarterly payments planned so April has no surprises.Preview
 Solo 401(k)A retirement plan built for self-employed income.Preview
- BookkeepingMonthly books and statements you can actually use.Preview
Industries we know
 Medical practicesPractice accounting and planningAccounting and planning for physician practices.Preview
- Private practice ownersPractice owner planningPlanning for physicians who own the practice.Preview
 Dental practicesAccounting, CFO and practice salesBooks, CFO help and planning for dental practices.Preview
 Law firmsFirm accounting and partner taxesFirm books, trust accounts and partner taxes.Preview
 Agencies and consultantsProject income and owner payProject income, contractors and owner pay.Preview
 Real estate agentsCommission income, done rightCommission income, deductions and quarterly taxes.Preview
 Contractors and tradesFrom job costs to tax planningJob costing, payroll and taxes for the trades.Preview
 Car washesAccounting and cost segregationMonthly accounting and cost seg for wash owners.Preview
 E-commerce sellersAmazon, Shopify and sales taxSeller books, sales tax and inventory, sorted.Preview
 RestaurantsBooks, payroll and planningBooks, payroll and planning for restaurant owners.Preview
 Insurance agentsAgency and commission incomeCommission income and agency accounting.Preview
 ProfessorsSalary plus consulting incomeUniversity salary plus consulting and royalties.Preview
 Content creatorsPlatform, sponsorship and brand-deal income.Preview
For real estate investors
Explore all Short-term rentalsHow short-term rentals can fit into your tax plan.Preview
- Cost SegregationSpeeding up depreciation on property you own.Preview
 Real estate pro statusReal estate professional status and what it takes.Preview
 1031 ExchangeRolling a property sale into your next purchase.Preview
 Passive Loss PlanningWhen rental losses can count, and when they wait.Preview
 Depreciation RecapturePlanning ahead for depreciation when you sell.Preview
- Augusta RuleRenting your home to your business for meetings.Preview
- BookkeepingMonthly books and statements you can actually use.Preview
For real estate syndicators
Explore all Syndication CPAAccounting and tax work for sponsors and GPs.Preview
- Fees and promoteHow sponsor fees and carried interest are taxed.Preview
- Returns and K-1sPartnership returns and investor K-1s on schedule.Preview
- Waterfalls and capitalCapital accounts and distributions that tie out.Preview
- Deal-level cost segDepreciation planned at the deal, felt by LPs.Preview
- Section 754 electionBasis step-ups when partners come and go.Preview
- State filings for K-1sInvestor state filings and composite returns.Preview
- Taxes for your LPsWhat investors see on their K-1s and returns.Preview
Tech and equity compensation
Explore all Equity CompensationRSUs, ISOs and ESPP, planned before you sell.Preview
 AMT PlanningKeeping AMT in view when you exercise options.Preview
- Mega Backdoor RothExtra Roth savings when your 401(k) plan allows it.Preview
- Tax-Loss HarvestingUsing investment losses to balance out gains.Preview
- Deduction BunchingTiming deductions so more of them count.Preview
- Estimated taxesQuarterly payments planned so April has no surprises.Preview
- Roth ConversionsMoving savings to Roth in the right years.Preview
- 1099 side incomeOrganizing 1099 side income and its expenses.Preview
For physicians and 1099 professionals
Explore all Locums S-CorpStructuring locum tenens income as a business.Preview
 MoonlightingSetting up moonlighting and side-shift income.Preview
 Multi-state taxesSorting out taxes when you work in several states.Preview
- 1099 side incomeOrganizing 1099 side income and its expenses.Preview
- Solo 401(k)A retirement plan built for self-employed income.Preview
- Estimated taxesQuarterly payments planned so April has no surprises.Preview
- Cash Balance PlanA larger retirement plan for high-earning owners.Preview
- Accountable PlanReimbursing business costs you pay personally.Preview
Retirement and wealth
Explore all- Cash Balance PlanA larger retirement plan for high-earning owners.Preview
- Solo 401(k)A retirement plan built for self-employed income.Preview
- Mega Backdoor RothExtra Roth savings when your 401(k) plan allows it.Preview
- Roth ConversionsMoving savings to Roth in the right years.Preview
- Tax-Loss HarvestingUsing investment losses to balance out gains.Preview
- Deduction BunchingTiming deductions so more of them count.Preview
 Retiring soonPlan withdrawals and income before you stop working.Preview
 Inheriting moneyWhat to file and decide after an inheritance.Preview
Life changes
- Retiring soonPlan withdrawals and income before you stop working.Preview
- Inheriting moneyWhat to file and decide after an inheritance.Preview
 Selling a businessPlan the tax side before you sign the deal.Preview
 Moving to a new stateResidency and part-year returns when you move.Preview
 Getting marriedTwo incomes, one plan, and your first joint return.Preview
 Having a babyCredits, accounts and planning for a growing family.Preview
 Selling your homeTax considerations when selling your primary residence.Preview
 Navigating divorceFiling status, dependents, and other tax considerations during divorce.Preview
Free · 30 minutes with our team to discuss your needs, our services, and fit.
Working with Taxstra
Guides and tools
Meet Bryan
- Watch: White Coat InvestorAs featured in White Coat Investor (Podcast Episode #459).
 Read: Bryan in the WCI blogHis article on which tax strategies are worth your time.Read the article
Educational information, not individualized tax advice. Eligibility depends on your facts.
A message from our founder
 Meet BryanWhite Coat Investor · Episode 459
WATCH BRYAN ON
WHITE COAT INVESTOR.
Episode 459: taxes, retirement, and real estate.
Explore the episodeREAD BRYAN IN
THE WCI BLOG.
Which Tax Strategies Are Actually Worth Your Time?
By Bryan Martin, CPA, MBA
A physician’s guide to weighing tax benefits against the time, complexity, and work each strategy requires.
Read Bryan’s articleOUR CORE SERVICES
Planning, filing, accounting, and advisory work together. Start with the support you need today, with room to adjust as your finances change.
PLAN.
Tax PlanningStop overpaying
Reduce liability before year-end with forward-looking tax strategies.
Start planningFILE.
Tax PreparationPeace of mind
Compliant, accurate filings for complex personal and business returns.
Get compliantKNOW.
Accounting DepartmentFinancial clarity
Reconciliation, financial statements, and monthly oversight, your full back office.
See what’s includedGROW.
CFO ServicesScale your business
Forecasting, KPI tracking, and strategic growth guidance.
Explore CFOYour planning map
The return is just the start.
Your return shows how you earn and what you own. Planning connects the pieces. Tap what applies to you and see which strategies sit where your pieces meet.
8 strategies on your map
Book your free 30-minute tax fit call
Educational, not individualized tax advice. Whether a strategy fits depends on your facts.
WHAT THE NUMBERS
LOOK LIKE.
See how a planning question plays out for someone in your situation. These hypothetical examples show the math and the details that matter.
Business owners
Find expenses that never made it into the books.
A sole proprietor collects $300,000 and records $90,000 of deductible expenses. A review finds another $12,000 of business software and insurance paid personally and left out of the books.
- Revenue
- $300,000
- Recorded deductible expenses
- − $90,000
- Additional eligible expenses
- − $12,000
- Corrected business profit
- $198,000
What this changes
Profit falls from $210,000 to $198,000 because the records now include costs the owner already paid. The $12,000 is a deduction, not a $12,000 tax saving.
What we would check
We would verify receipts, business purpose, payment timing, and that nothing was reimbursed or deducted twice. This assumes fully deductible current expenses; personal costs and capital purchases need different treatment.
Real estate investors
Separate rental cash flow from taxable income.
A long-term residential rental brings in $36,000 a year with $16,000 of deductible operating costs. Its building has a $275,000 depreciable basis, excluding land.
- Rent collected
- $36,000
- Deductible operating costs
- − $16,000
- Full-year depreciation: $275,000 ÷ 27.5
- − $10,000
- Rental income after these deductions
- $10,000
What this changes
There is $20,000 left before debt principal, capital spending, and income taxes, but only $10,000 of rental income after depreciation in this example.
What we would check
This assumes a full year after the placed-in-service year, standard 27.5-year GDS depreciation, no personal use, and no other adjustments. First and final years use a mid-month convention. Depreciation reduces basis and can increase tax on a later sale; rental losses do not automatically offset wages.
Short-term rental investors
Put the numbers behind a rental purchase.
$450,000 short-term rental with an average guest stay of 7 days or fewer, and an owner who materially participates.
A cost segregation study reclassifies $180,000 of components into 5-, 7-, and 15-year property.
- Illustrative purchase price
- $450,000
- Reclassified components
- $180,000
- Assumed federal marginal rate
- 35%
- Illustrative year-one federal tax reduction
- $63,000
What this changes
With 100% bonus depreciation, permanent for property acquired and placed in service after January 19, 2025, the full $180,000 is deductible in year one as a non-passive loss.
At a 35% federal marginal rate that is roughly $63,000 less federal tax in year one, with no change to cash flow. Recapture applies on sale, and state treatment varies.
Illustrative composite, not a client result. Figures match the 2026 rules on our STR service page; eligibility depends on your facts.
High-income professionals
Account for stock compensation already taxed as wages.
An employee receives vested employer shares at no cost, with $80,000 included in W-2 wages. They later sell those same shares for $86,000.
- Sale proceeds
- $86,000
- Basis from compensation already included in income
- − $80,000
- Capital gain before selling costs
- $6,000
What this changes
The sale produces a $6,000 capital gain. Treating the shares as having zero basis would incorrectly show an $86,000 gain on top of the wages already reported.
What we would check
We would reconcile the W-2, vesting or settlement records, and brokerage statement for the exact shares sold. This assumes the full $80,000 became basis and there were no later adjustments. The holding period determines whether the gain is short- or long-term.
Physicians & 1099 professionals
Coordinate a hospital paycheck with 1099 income.
A physician with W-2 and locum income files jointly, had 2025 AGI above $150,000, and had $80,000 of prior-year tax for safe-harbor purposes. Expected 2026 federal withholding is $40,000.
- Prior-year safe-harbor target: $80,000 × 110%
- $88,000
- Expected federal withholding
- − $40,000
- Amount to cover with estimated payments
- $48,000
- Four equal, timely installments
- $12,000 each
What this changes
This gives the physician a payment schedule using the prior-year safe harbor. It does not mean their final 2026 tax will be $88,000; a balance may still be due.
What we would check
This assumes a full 12-month prior-year return, ordinary safe-harbor rules, and payments made by each required deadline. We would also compare 90% of current-year tax, check actual withholding, and calculate state obligations separately. Uneven income may warrant the annualized method.
Hypothetical illustrations, not client results or promised savings. Educational, not individualized tax advice. Federal rules checked September 12, 2026; state treatment may differ.
Book your free 30-minute tax fit callFROM FILING.
TO PLANNING.
Start with a conversation, then build a plan that stays connected to your return and the decisions you make throughout the year.
Initial Consultation
A free 30-minute conversation with our team about your situation, service fit, and next steps.
Deep Dive
After engagement, we review your returns, income, and upcoming decisions to identify planning opportunities.
Custom Tax Plan
You receive a written plan that explains our recommendations, the assumptions behind them, and the steps needed to put them into practice.
Year-Round Execution
We follow through on the agreed work and revisit the plan during the year. New income, investments, or business decisions can change what needs attention.
Detailed document review, eligibility analysis, and tailored modeling begin after engagement. Your proposal specifies the fee and scope.
Book your free 30-minute tax fit callThe tools we use with you
Stay connected throughout the year.
Share documents, keep your books current, and stay in touch with our team through the tools our team works in. These are the services we use with you, not a Taxstra app. Tap one to see what it does.
Tap or hover an app
Your tax team, in your pocket
Video or phone calls, document uploads and messages, with secure, nationwide collaboration.
Your documents live in our TaxDome client portal, with bank-level encryption, e-signatures and secure messaging.
 QuickBooks
Cloud accounting
Real-time financial tracking with automated bank feeds and monthly reports.
- ✓Bank feeds synced
- ✓Monthly report ready
- …Books reconciled
Example screen
 UltraTax CS
Professional tax
Preparation software for complex and multi-state returns.
- ✓Federal return
- ✓State returns
- …Review and e-file
Example screen
 TaxDome
Secure portal
Bank-level encryption for documents, e-signatures, and client communication.
- ✓Documents uploaded
- ✓Engagement letter signed
- …New message from your team
Example screen
 ADP
Payroll services
Full-service payroll processing with tax deposits, W-2s, and compliance.
- ✓Payroll run scheduled
- ✓Tax deposits on file
- …W-2s at year end
Example screen
 Engineered Tax
Cost segregation
Specialized real estate studies that accelerate depreciation and maximize deductions.
- ✓Property details collected
- ✓Engineering study
- …Report for your return
Example screen
Tax plan
A clear path forward: the priorities for your next conversation with our team.
Your tax planPreview
A clear path forward.Priorities for your next conversation
Planning progress1 of 3 steps
Financial pictureDocuments organized
2
Strategy reviewRetirement · entity · investments
3
Put your plan to workEstimates and next steps
Example screen
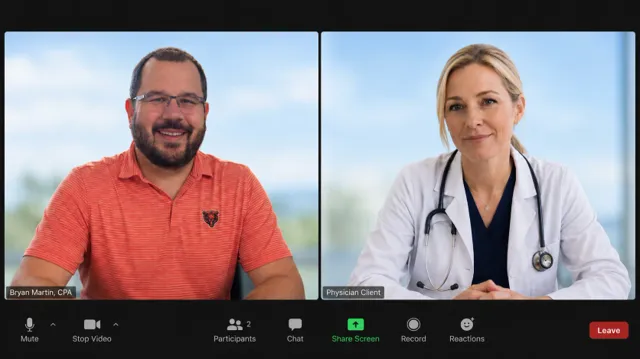
Your tax team
Video or phone calls with our team, wherever you are based.
Example screen
One connected stack
We use these tools to keep the information behind your books, tax plan, and returns organized.
One shared picture for your books, plan and returns.
Example screen
2026 state guides
Where you live changes your taxes.
Pick a situation and every state is shaded by our published 2026 ranking for it. Hover or tap a state, then open the full guide.
Top 5 for 1099 physicians
- 1Iowa8.4 / 10
- 2South Dakota8.4 / 10
- 3North Dakota7.9 / 10
- 4Tennessee7.9 / 10
- 5Texas7.8 / 10
Physician contractor tax, cost and lifestyle grade
Rankings from Taxstra's 2026 state guides, updated September 12, 2026. Methodology and sources are on each guide. Educational research, not individualized tax advice.
Showing Best States for 1099 Physicians.
Ready to talk?
A free 30-minute call with our team about your needs, how we can help, and whether we are a good fit.
Book your free 30-minute tax fit callTax planning slots are limited before year-end.
Simple return? Welcome. Or call (217) 788-0750.
REAL CLIENTS.
IN THEIR OWN WORDS.
“I am very pleased with Taxstra. They handle all my business and personal accounting. Payroll, monthly P&L, taxes, and tax returns. I highly recommend them.”
“Bryan, my accountant, is truly one of the smartest people I know. He has an incredible understanding of the value of a dollar and always finds ways to maximize financial benefits.”
“I recently had the pleasure of working with Taxstra, and I must say, the experience exceeded my expectations. From start to finish, their professionalism, expertise, and customer care were outstanding.”
“Exactly what I was looking for in a CPA/Tax Prep Company. Returns were filed on time. Highly recommend Bryan Martin and his team to everyone who needs to have their taxes incl. biz taxes done!”
“From my perspective, I have very complicated taxes and cannot say enough in appreciation for Bryan to figure it all out: His patience, his expertise, his persistence made all the difference in the world!”
“Brian and his team were very helpful even though I was running behind on taxes. They made me feel comfortable. Everything went great and I'm all caught up.”
Reviews from Google · Scroll to explore
COMMON QUESTIONS
ABOUT TAXSTRA.
Find answers by topic, from working with Taxstra to planning around a more complex financial life.
Reviewed by Bryan Martin, CPA, Managing Partner and Founder of Taxstra. Last reviewed .
What services does Taxstra provide?
Taxstra provides comprehensive tax preparation, strategic tax planning, bookkeeping, payroll services, IRS representation, and specialized consulting for real estate investors, physicians, and business owners.
How is Taxstra different from other CPA firms?
We bring planning, preparation, and accounting into the same conversation. Our work focuses on physicians, business owners, real estate investors, and high-income households whose decisions need to be considered together. We explain the options and follow through on the work in your engagement.
What is the difference between tax planning and tax preparation?
Tax preparation uses your records to report the year’s activity. Tax planning looks ahead at decisions you can still make, such as buying a property or changing how you pay yourself. The plan and the return need to stay connected.
Do you offer remote tax and accounting services?
Yes. We work with clients in all 50 states from our office in Springfield, Illinois. Documents move through our secure TaxDome portal, and we meet by phone or video, so you can work with us wherever you are based.
What is the process for becoming a new client?
We begin with a free 30-minute conversation about your situation and the help you need. If we agree to work together, your proposal sets out the scope and fee. Detailed return review and planning begin after engagement, followed by the implementation and filing work included in that scope.
How do you determine your fees?
Engagements are scoped after your free consultation. Fees depend on the complexity of your situation and the work involved, and your written proposal lists the fee and scope before any work begins. No surprises.
When should I start tax planning?
Bring us in while you are considering a decision. A new job, business, or property purchase gives us something concrete to work through together. You can also start with a review of your current arrangements if you want to understand what deserves attention this year.
Do I need to pay estimated taxes?
If you expect to owe at least $1,000 in tax after subtracting your withholding and refundable credits, or if you are self-employed, you generally need to make estimated tax payments quarterly to avoid penalties.
How can I save for retirement while lowering my taxes?
Contributing to tax-advantaged retirement accounts like a 401(k), SEP IRA, Solo 401(k), or Traditional IRA can reduce your taxable income for the year while helping you build a nest egg for the future.
Should I form an LLC or an S-Corp?
It depends on your income level, business goals, and liability concerns. An LLC offers flexibility and protection, while an S-Corp can provide significant tax savings on self-employment taxes for profitable businesses (generally above $50-70k net income).
Can you represent me in an IRS audit?
Yes. As CPAs, we have unlimited rights to represent taxpayers before the IRS. We can handle the communication, attend meetings, and negotiate on your behalf, so you do not have to speak with the IRS directly.
What should I do if I receive a notice from the IRS?
Don't panic, but don't ignore it. Send a copy of the notice to us immediately. We will review it, explain what it means, and help you draft the appropriate response within the required timeframe.
How long should I keep my tax records?
The IRS generally recommends keeping tax returns and supporting documents for at least three years. However, for property, business assets, or if you underreported income by more than 25%, you should keep records for 6-7 years.
Why is bookkeeping important for my business?
Accurate bookkeeping ensures you have a clear picture of your financial health, makes tax filing easier and more accurate, helps you manage cash flow, and is essential if you are ever audited.
Can I deduct my home office expenses?
If you use a portion of your home exclusively and regularly for your business (and you're self-employed), you may be able to deduct a percentage of your home expenses, such as mortgage interest, insurance, utilities, and repairs.
How is cryptocurrency taxed?
The IRS treats cryptocurrency as property. This means you may owe capital gains tax when you sell, trade, or spend crypto if it has increased in value since you acquired it. We help track and report all crypto transactions.
What documents do I need to provide for tax preparation?
We'll need W-2s, 1099s, investment statements, property records, business income/expense summaries, prior year returns, and any relevant receipts. Our secure client portal makes uploading documents easy.
Do you offer payment plans for your services?
Yes, we offer flexible payment options for our tax planning and preparation services. We can discuss payment arrangements during your initial consultation to find what works best for you.
What is the SALT cap and how does it affect me?
For 2026 the State and Local Tax (SALT) deduction is capped at $40,400 ($20,200 if married filing separately). The cap phases down by 30% of modified AGI above $505,000, but never below $10,000, and it is scheduled to return to $10,000 in 2030. Many high earners above the phase-down still land at the $10,000 floor, so PTE elections and business structuring still matter.
Can you help with back taxes or unfiled returns?
Absolutely. We specialize in helping clients get caught up on unfiled returns and negotiate with the IRS on back taxes. The sooner you address this, the more options are available to resolve the situation.
How does the 'Short-Term Rental Loophole' work for out-of-state properties?
The 'STR Loophole' (Reg. Section 1.469-1T(e)(3)(ii)(A)) allows you to reclassify rental losses as non-passive if the average stay is 7 days or less and you materially participate. This means your rental losses (depreciation) can offset your active W-2 income, even if the property is in Florida and you live in Illinois.
What is a 1031 exchange and how can it defer my taxes?
A 1031 exchange allows you to swap one investment property for another of like-kind and defer capital gains taxes indefinitely. You must follow strict timelines: 45 days to identify replacement properties and 180 days to close.
What is cost segregation and why should I care?
Cost segregation is an engineering-based study that accelerates depreciation on your property by reclassifying components (carpet, fixtures, landscaping) into shorter depreciation periods (5, 7, or 15 years vs. 27.5 or 39 years). This provides massive upfront tax deductions.
What are the tax benefits of investing in real estate?
Real estate offers numerous tax benefits: depreciation deductions, mortgage interest deductions, property tax deductions, 1031 exchange deferrals, opportunity zone benefits, and the potential for capital gains treatment on sales.
Can I use bonus depreciation on real estate?
Yes. A cost segregation study identifies the 5, 7 and 15-year components of a building. For property acquired and placed in service after January 19, 2025, those components qualify for 100% bonus depreciation, which the 2025 tax law made permanent. That can create a large first-year deduction; whether it offsets your other income depends on the passive activity rules.
What is Real Estate Professional Status (REPS)?
REPS allows you to treat all your rental activities as non-passive, enabling rental losses to offset any income. You must spend 750+ hours in real estate activities AND more time in real estate than any other profession.
Should I hold rental properties in an LLC?
LLCs provide liability protection and flexibility. For tax purposes, single-member LLCs are disregarded entities. For multiple properties, we often recommend a holding company structure with separate LLCs for each property.
How do I track my rental property expenses properly?
Keep detailed records of all income and expenses, including repairs, improvements, insurance, property management fees, travel to properties, and supplies. Use separate bank accounts for each property and categorize everything in your bookkeeping system.
What is the difference between a repair and an improvement?
Repairs (fixing a leak, repainting) are deductible in the current year. Improvements (new roof, renovation) must be capitalized and depreciated over time. The distinction matters significantly for your tax planning.
Can I deduct travel expenses to visit my rental properties?
Yes, travel expenses to manage, maintain, or collect rent from your rental properties are deductible. This includes airfare, hotels, rental cars, and meals (50%) if the primary purpose is business-related.
How can a physician reduce taxes on moonlighting or 1099 income?
Moonlighting and 1099 income open planning options a W-2 job does not. Depending on your numbers, that can include deducting business expenses, an S corp election once profit justifies payroll costs, a Solo 401(k), and a state pass-through entity tax election. For 2026, a Solo 401(k) allows up to $72,000 combined, but the $24,500 employee deferral is shared with any employer 401(k) or 403(b). The pass-through election can work around the SALT cap, which is $40,400 for 2026 and phases down toward $10,000 at higher incomes.
What is the typical process for new physician clients?
We start with a free 30-minute initial consultation to verify fit. If we proceed, we perform a Deep Dive analysis of your prior 2 years of returns, build a forward-looking Tax Plan (entity structure, retirement, real estate), and handle your filings year-round.
Should I form an S-Corp for my locum tenens or consulting income?
If you have $50k+ in net 1099 income, an S-Corp can save you thousands in self-employment taxes. We analyze your specific situation to determine the optimal salary/distribution split and potential savings.
What retirement accounts should physicians maximize?
Employed physicians usually start with the employer 403(b) or 401(k) ($24,500 for 2026, plus $8,000 more at 50 or older), a backdoor Roth IRA, and an HSA if eligible. With 1099 income, a Solo 401(k) adds employer contributions within a $72,000 total for 2026, and a cash balance plan can shelter much more for older, high-earning physicians.
How can I reduce taxes on my W-2 hospital income?
Maximize pre-tax retirement contributions, review your W-4 withholding, utilize HSA accounts, consider real estate investments with accelerated depreciation, and if married, review filing status and income splitting strategies.
What is the backdoor Roth IRA strategy?
High-income physicians can't contribute directly to a Roth IRA. The backdoor strategy involves contributing to a non-deductible Traditional IRA, then immediately converting to a Roth. Be cautious of the pro-rata rule if you have other IRA balances.
Can physicians benefit from real estate investments?
Absolutely. Many physicians use short-term rentals with the STR Loophole to generate passive losses that offset their high W-2 income. Combine this with cost segregation for accelerated depreciation and significant tax savings.
What is a defined benefit plan and is it right for me?
A defined benefit (pension) plan allows for contributions of $200k+ annually, far exceeding 401(k) limits. It's ideal for older physicians with high, stable 1099 income who want to accelerate retirement savings and reduce taxes.
How do I handle taxes if I work in multiple states?
Locum tenens physicians often work in multiple states. We track your days worked in each state, file the required returns, and ensure you get credit for taxes paid to avoid double taxation.
How do my student loans interact with my taxes?
If you are on an income-driven repayment plan, your monthly payment is calculated from your tax return: your AGI and filing status drive the number. Pre-tax retirement contributions lower your AGI (and therefore the payment), and MFS vs MFJ determines whose income counts. We model the tax side of those decisions; we do not advise on loan or repayment plan selection.
When should I switch from an LLC to an S-Corp?
Generally, once your net business income exceeds $50-70k annually, the self-employment tax savings from an S-Corp exceed the additional costs (payroll, compliance). We'll model your specific situation to find the crossover point.
What payroll services do you provide?
We offer full-service payroll processing through ADP, including paycheck calculation, direct deposit, tax withholding, quarterly 941 filings, annual W-2/W-3 preparation, and state unemployment reports.
Is there a tax benefit to hiring my children?
Yes! Wages paid to your children under 18 in a sole proprietorship are exempt from Social Security and Medicare taxes. Their income up to the standard deduction is tax-free, and they can contribute to a Roth IRA.
What business expenses are deductible?
Most ordinary and necessary business expenses are deductible: office supplies, software, professional services, insurance, advertising, travel, meals (50%), vehicle expenses, and more. Proper documentation is key.
How does the Qualified Business Income (QBI) deduction work?
The QBI deduction allows eligible business owners to deduct up to 20% of their qualified business income. Limitations apply based on income level, type of business (SSTB), and W-2 wages/property basis.
Should I take a salary or distributions from my S-Corp?
You must pay yourself a 'reasonable salary' subject to payroll taxes. Any remaining profits can be distributed without payroll taxes. We help determine the optimal split to maximize tax savings while staying IRS-compliant.
What is the Augusta Rule and can I use it?
The Augusta Rule (Section 280A(g)) allows you to rent your home to your business for up to 14 days per year tax-free. The business gets a deduction, and you receive tax-free rental income. Documentation is critical.
How do I deduct vehicle expenses for my business?
You can use the IRS standard mileage rate (72.5 cents a mile for January through June 2026 and 76 cents from July 1, 2026) or actual expenses (gas, insurance, depreciation). Keep a mileage log with the business purpose, date and miles for each trip, and compare both methods each year.
Can I deduct health insurance premiums?
Self-employed individuals can deduct 100% of health insurance premiums for themselves, spouse, and dependents. S-Corp shareholders must include premiums in W-2 wages, then deduct on their personal return.
What retirement plans are available for small business owners?
Options include a SEP IRA (employer contributions of up to 25% of pay, or about 20% of net self-employment earnings), a Solo 401(k) for owners without employees ($24,500 of employee deferrals for 2026 plus employer contributions, up to $72,000 combined), a SIMPLE IRA, and defined benefit or cash balance plans. The best choice depends on your income, employees, and savings goals.
What are the biggest tax planning mistakes people make?
Waiting until tax season to plan, missing estimated tax payments, not maximizing retirement contributions, ignoring entity structure optimization, and failing to document deductions properly. Proactive planning prevents these issues.
How can I reduce my taxable income legally?
Maximize retirement contributions, harvest capital losses, bunch deductions, utilize HSAs, consider charitable giving strategies (donor-advised funds, QCDs), and structure your business and investments efficiently.
What is tax-loss harvesting?
Tax-loss harvesting involves selling investments at a loss to offset capital gains. These losses can offset gains dollar-for-dollar, plus $3,000 of ordinary income annually. Unused losses carry forward indefinitely.
Should I itemize deductions or take the standard deduction?
Take whichever is higher. For 2026 the standard deduction is $16,100 (single), $32,200 (married filing jointly) or $24,150 (head of household). If your mortgage interest, state and local taxes (capped at $40,400 for most filers in 2026), and charitable gifts add up to more, itemizing may benefit you.
What is the pass-through entity (PTE) election?
Many states let pass-through entities (S corps and partnerships) pay state income tax at the entity level, where it is deductible federally. That works around the SALT cap, which is $40,400 for 2026 and phases down toward $10,000 once modified AGI passes $505,000, so it is often most valuable for high earners in high-tax states.
How do capital gains taxes work?
Short-term gains (assets held one year or less) are taxed as ordinary income. Long-term gains (held more than one year) are taxed at 0%, 15%, or 20% depending on income. High earners may also pay a 3.8% Net Investment Income Tax.
What is income shifting and is it legal?
Income shifting involves moving income to family members in lower tax brackets through legitimate means like hiring children, gifting appreciated assets, or family limited partnerships. Done properly, it's completely legal.
Should I accelerate income or defer it to next year?
This depends on your expected tax rates in each year. If you expect lower income or rates next year, deferring income makes sense. If rates will increase, accelerating income and deductions becomes the better strategy.
What charitable giving strategies reduce taxes the most?
Donor-advised funds allow bunching multiple years of gifts, Qualified Charitable Distributions (QCDs) from IRAs reduce AGI, and donating appreciated stock avoids capital gains while providing a full deduction.
How do Opportunity Zones work for tax deferral?
Investing capital gains in Qualified Opportunity Funds defers and potentially reduces those gains. Hold for 10+ years, and any appreciation on the OZ investment is tax-free. It's a powerful tool for real estate investors.
What triggers an IRS audit?
Common triggers include: high income with unusual deductions, discrepancies between reported income and 1099s/W-2s, excessive charitable contributions, cash-heavy businesses, home office deductions, and claiming hobby losses as business losses.
What are my rights during an IRS audit?
You have the right to professional representation, to know why you're being audited, to confidentiality, to appeal any decision, and to request an extension if needed. You never have to meet with the IRS alone.
What is the penalty for not filing taxes on time?
The failure-to-file penalty is 5% per month up to 25% of unpaid tax. The failure-to-pay penalty is 0.5% per month up to 25%. Always file on time, even if you can't pay, the filing penalty is much higher.
Can the IRS forgive my tax debt?
Yes, through an Offer in Compromise (OIC), the IRS may settle for less than owed if you can prove paying in full would cause financial hardship. We can evaluate your eligibility and negotiate on your behalf.
How do I request an extension to file my taxes?
File Form 4868 by April 15th for an automatic 6-month extension to file (not pay). If you owe taxes, estimate and pay by April 15th to avoid penalties and interest. We can handle this filing for you.
What is the statute of limitations on IRS audits?
Generally, the IRS has 3 years from filing to audit your return. This extends to 6 years if you underreported income by more than 25%, and there's no limit for fraud or unfiled returns.
What is innocent spouse relief?
If your spouse or ex-spouse improperly reported items on a joint return without your knowledge, you may qualify for innocent spouse relief and not be held liable for the resulting taxes, penalties, and interest.
How do I set up an IRS payment plan?
We can help you request an installment agreement. Short-term plans (120 days or less) have no setup fee. Long-term plans have fees but allow monthly payments. Staying compliant with all future filings is required.
What should I do if I can't afford to pay my taxes?
Don't panic, you have options. We can help you set up a payment plan, request Currently Not Collectible status, or negotiate an Offer in Compromise. The worst thing to do is ignore the problem.
Do I need to report foreign bank accounts?
Yes, if your foreign accounts exceed $10,000 at any point during the year, you must file an FBAR. Additional reporting (Form 8938) may be required depending on your filing status and asset values. Penalties for non-compliance are severe.
Educational content provides general information, not individualized tax, legal, or accounting advice.
Your next move.
With a plan.
A free 30-minute conversation with our team about your situation, service fit, and next steps.
Tax planning slots are limited before year-end.
Or call (217) 788-0750Live availability
Book a free 30-minute consultation with our team.
Tell us what you need, learn how Taxstra can help, and explore whether our services are a good fit.
- Who you talk toA member of our team, for 30 minutes, about your situation and goals.
- What you learnHow we work, which services fit, and what working together looks like.
- What it costsEngagements are scoped after your free consultation. If you go ahead, your proposal lists the fee and scope, and planning and tax advice begin then.
Free. 30 minutes. Tax planning slots are limited before year-end.
Prefer the phone? (217) 788-0750Open the scheduler on its own page
What happens after you book?
We’ll talk about your situation.
Tell us what’s changing, where you need help, and what you want from a tax team.
Bring your questions.
A high-level overview is enough for the first conversation. Keep your tax documents for the secure onboarding process.
We’ll discuss the fit.
If we’re a fit, we’ll discuss scope and next steps. Detailed analysis begins after engagement.