
Schedule E (Form 1040) Explained for Rental Property Owners
A plain-English guide to rental income, deductible expenses, depreciation, passive losses, documentation, and the lines on Schedule E.
A guide by Taxstra Tax & Accounting · CPA-led tax strategy for business owners
Quick Answer
Schedule E (Form 1040) is the IRS form used to report supplemental income and loss from rental real estate, royalties, partnerships, S-corporations, estates, and trusts. For most rental property investors, Schedule E is where you report rental income, deductible expenses (mortgage interest, repairs, insurance, property management), and depreciation. Net rental income flows to your 1040 and is generally classified as passive income under IRC §469.
Rental income on your return? Don't leave depreciation on the table.
Book a free 30-minute consultation with our team. Tell us what you need, learn how Taxstra can help, and explore whether our services are a good fit. Tax advice, document reviews, and analysis require a paid engagement.
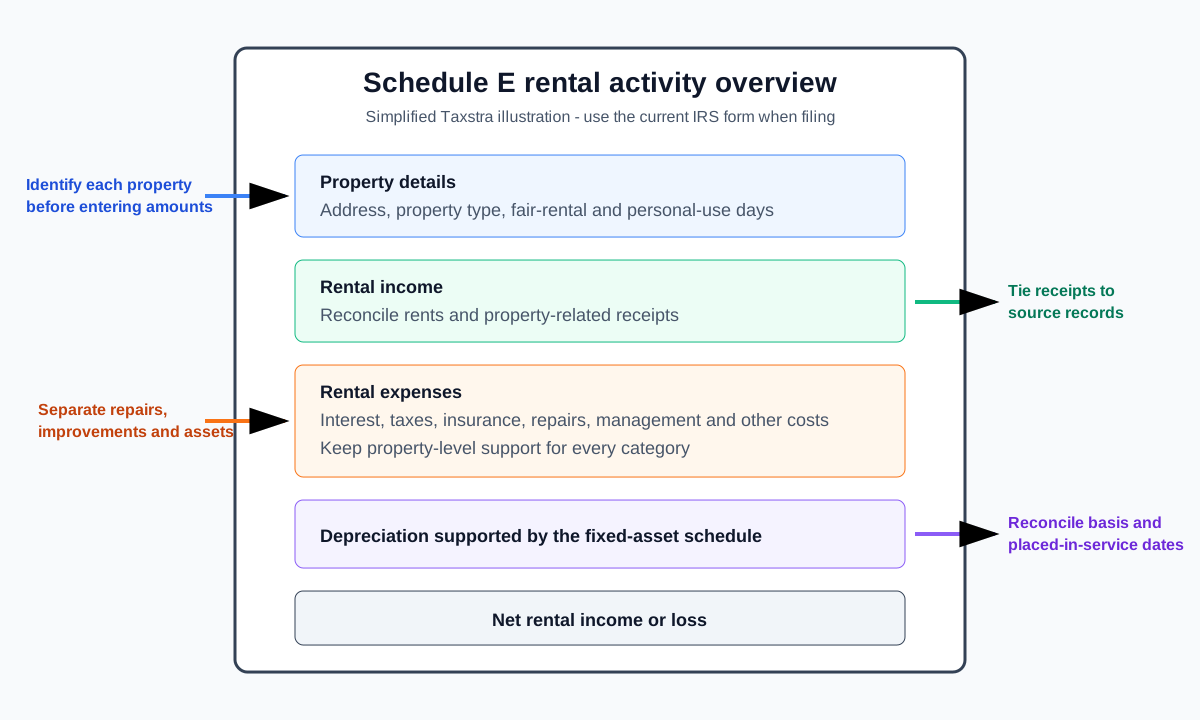
What Is IRS Schedule E?
Schedule E (Supplemental Income and Loss) is the tax form used to report income or loss from rental real estate, royalties, partnerships, S corporations, estates, and trusts. It is the cornerstone of real estate investor tax planning.
For real estate investors, this is your P&L statement for the IRS. If you need help with rental bookkeeping, check out our landlord accounting services. It is where you tell the story of your rental business: how much rent you collected, what you spent on repairs, insurance, and taxes, and most importantly, how much depreciation you are claiming.
Completed Schedule E Example
Consider a residential rental property rented for the full 12 months at $2,400/month.
| Gross Rental Income | $28,800 |
| Deductible Expenses | |
| Mortgage Interest | $12,000 |
| Property Tax | $4,200 |
| Insurance | $3,600 |
| Repairs & Maintenance | $2,400 |
| Property Management | $1,800 |
| Other Expenses | $4,000 |
| Total Operating Expenses | $28,000 |
| Operating Income (Before Depreciation) | $800 |
| Illustrative full-year depreciation ($250K building ÷ 27.5 years) | ($9,091) |
| Net Loss Reported on Schedule E | ($8,291) |
Hypothetical established residential rental using a full-year straight-line illustration, with land excluded and no personal use. First-year and final-year depreciation use a convention and can differ. The $8,291 activity loss is not automatically deductible against wages. Prior depreciation affects basis and can create special tax treatment at sale.
Own rentals? Schedule E is where the planning shows up.
Depreciation, the passive loss rules, and how a property is used decide whether a rental loss offsets your other income or just carries forward. Those calls are made during the year, not on the form. Book a free 30-minute consultation with our team to talk through your rentals and whether Taxstra is a fit. See how we work with real estate investors.
Who Must File Schedule E?
Schedule E can apply to owners reporting rental real estate or royalty activity and to taxpayers reporting pass-through items from partnerships, S corporations, estates, or trusts. The correct form and section depend on the activity and ownership structure.
Schedule E: The Line-by-Line Breakdown
Click on any line item below for a deep-dive explanation, specific examples, and audit flags to watch out for.
Schedule E Rental Income
Reconcile gross rents and other property receipts to bank deposits, property-manager statements, and any information returns. Keep refundable security deposits separate from amounts that become rental income.
Schedule E Rental Expenses
| Category | Examples to reconcile | Records to retain |
|---|---|---|
| Income | Rent, fees, retained deposits | Leases, platform and manager statements |
| Operating costs | Advertising, insurance, utilities, management | Invoices, receipts, bank statements |
| Repairs | Property-specific maintenance and repair work | Invoices, photos, work descriptions |
| Interest and taxes | Rental debt interest and property taxes | Form 1098, loan and tax statements |
| Depreciation | Building and eligible property components | Closing statement, basis and fixed-asset schedules |
How Depreciation Is Reported
Depreciation starts with supportable basis, land allocation, asset classification, and placed-in-service dates. The resulting depreciation schedule supports the amount reported for the property; cost-segregation and prior-year corrections require a separate analysis.
Passive Activity Loss Rules
Rental losses are generally evaluated under the passive-activity rules before they can offset other income. Participation, income, basis, at-risk limits, grouping, and disposition facts can all change the amount currently deductible.
Real Estate Professional Status
Real estate professional status is not a box on Schedule E. It is a qualification and material-participation analysis that can affect whether rental losses are passive. Review the REPS guide before relying on losses against non-rental income.
Partnerships, S Corporations and Schedule E
Schedule E also reports certain amounts passed through on Schedule K-1. Do not combine direct property activity with partnership or S-corporation items without reconciling each entity, basis schedule, and activity classification.
Schedule E Recordkeeping Checklist
- Leases and closing statements
- Property-manager and platform reports
- Bank and credit-card statements
- Receipts and vendor invoices
- Mileage and travel support
- Mortgage and property-tax statements
- Fixed-asset and depreciation schedules
- Prior-year returns and suspended-loss records
Source check September 29, 2026. Official references: IRS Schedule E, Schedule E instructions, Publication 527: rental reporting and guest services, and Publication 925: passive activity and at-risk rules.
Short-Term Rentals and Schedule E
One of the most common mistakes we see involves Short-Term Rentals (Airbnbs). See our full guide on the short-term rental tax loophole.
Two separate questions: substantial services for guest convenience can affect Schedule C reporting. Average customer use and material participation determine the Section 469 passive-loss analysis. A short stay alone does not require Schedule C.
Schedule E Mistakes to Avoid
1. Deducting Improvements as Repairs
Evaluate whether work improves the property or keeps it in ordinary operating condition. The scope, asset classification, and applicable elections matter; a label on an invoice does not settle the treatment.2. Missing Depreciation
Keep a complete depreciation schedule. Basis generally reflects allowable depreciation even when it was not claimed, and disposition treatment depends on the property and prior deductions.3. Refinancing Cost Confusion
Separate interest from financing charges and other closing costs. Interest treatment depends on how borrowed funds are used; financing costs can require allocation or amortization.4. Commingling Funds
Keep clear records separating rental transactions from personal spending. Separate accounts can simplify reconciliation; entity liability questions require legal advice.Managing Multiple Properties? Let Us Handle the Books.
Rental property accounting gets complex fast, depreciation schedules, passive loss tracking, cost segregation studies, and multi-property reporting. Our monthly accounting service helps organize reconciliations and reporting for tax preparation.
Schedule E FAQs
Next Steps
Filing it yourself is fine. Optimizing it is where the money is.
Getting the form right keeps you out of trouble. The strategies below are what actually lower the bill.
The STR Loophole
Review the customer-use and participation tests before analyzing whether an STR loss can offset other income.
Real Estate Professional Status
REPS qualification and material participation can change passive-loss treatment. Basis, at-risk, and other loss limits still apply.
Form 8582 and Passive Loss Rules
How Form 8582 banks suspended rental losses, when the $25,000 allowance applies, and what it takes to use those losses against other income.
Watching suspended passive losses pile up on Form 8582?
Book a free 30-minute consultation with our team. Tell us what you need, learn how Taxstra can help, and explore whether our services are a good fit. Tax advice, document reviews, and analysis require a paid engagement.
Discuss accounting and tax services for your rentals
Book a free 30-minute consultation with our team to discuss your needs, services, and fit. Personalized advice, document reviews, and calculations require a paid engagement.
Related Taxstra resources
Continue with the services, planning tools, and explainers most relevant to this topic.
- form 3115
- California Capital Gains Tax
- Heloc On Rental Property
- Accountant For Landlords
- Capital Gains Tax Calculator
- Rental Property Depreciation Calculator
- Real Estate CPA
- Cost Segregation Study
- Real Estate Professional Status
- Short Term Rental Loophole
- 1031 Exchange Calculator
- Cap Rate Calculator
- Property Tax Calculator
- Passive Activity Loss Calculator