See if Taxstra fits your physician taxes.
A free 30-minute call with our team about your needs, how we can help, and whether we are a good fit.
Free · 30 minutes · video
Fit check before you book
- Best for: 1099 and locum physicians, physicians weighing an S corp, and high-income W-2 physicians with rentals, side income or equity.
- Simple W-2 return? Welcome too. Not every physician needs a full tax plan, and we will match you to the right service level, from straightforward preparation to year-round planning.
- Who you talk to: Our onboarding team. We may talk about your tax situation in general terms, but the tax plan and advice come after you engage, once we have the full picture.
- What you leave with: Which services fit, what an engagement looks like, and the cost range. If it is a fit, a tailored proposal follows.
Loading calendar
5.0 from 113 Google reviews. 1,000+ clients. All 50 states.
Prefer to talk right now? Call (217) 788-0750
How to prepare
The booking form asks about:
- Your income types: W-2, 1099, locum, moonlighting or rental
- Any entities you own (LLC, PLLC, S corp)
- Your projected income for this year
- The states where you live and work
- The services you want help with
- How you heard about us
Rough numbers are fine. You do not need to send documents for this call.
Your tax plan comes later
The call is not where you get a tax plan. We may talk through your situation in general terms, but we do not give advice until an engagement starts, because we would not have the full picture yet. Return or document reviews, S corp analysis and savings estimates are part of the paid work too.
No guaranteed-savings gimmicks and no pressure. Just a straight answer on whether we are the right firm for you.
Live on the White Coat Investor podcast.
Our founder, Bryan Martin, CPA, on tax strategies for high-income physicians.
Your tax return is not the strategy.
By the time most physicians send documents to their CPA, the best planning moves are already gone. It is most expensive for 1099 physicians, who may need entity structure, payroll, retirement-plan coordination, quarterly planning, and clean accounting in place before year-end.
The other version: your entity is right-sized, payroll and reasonable comp are handled, estimates are paid on schedule, and your books are clean. Nothing gets planned in April that should have been planned in June. That is what year-round planning buys you.
The problem is different. The need for planning isn't.
1099 Physicians
Primary fitYou may need structure before income gets messy.
- Large self-employment tax exposure
- No clean accounting system
- No payroll setup
- Missed retirement-plan opportunities
- Poor quarterly estimate planning
- Late or nonexistent S-Corp analysis
W-2 Physicians
You may still have real planning opportunities.
- Large tax bills
- Rental & short-term rental properties
- Moonlighting income
- Backdoor Roth issues
- Charitable planning
- Equity compensation
- Dual-income household complexity
The S-Corp question shouldn't be guesswork.
An S-Corp can be powerful for the right physician, but only if the numbers, payroll, compliance, retirement coordination, and admin burden actually make sense. We run the break-even before you form an entity or keep defaulting to sole proprietor.
What a $600K 1099 physician overpays with no plan in place.
A hypothetical physician, run through the structure we would actually build, with every number shown and 2026 federal rules. Illustrative only. Savings vary by client and situation, and results are not typical.
Dr. Avery (hypothetical)
Independent / locum tenens physician, paid on a 1099
How to read it: figures use 2026 federal rules and a blended 30% federal marginal rate. These physicians sit in the 32% to 35% brackets, and as deductions stack the last dollars fall into 24%, so 30% is the honest middle. State income tax is additional.
Elect S-corp status
PermanentA reasonable salary plus distributions; the distributions skip Medicare tax.
$350K salary, Medicare saved about $7,756 less payroll cost
Solo 401(k) + cash balance plan
DeferralThe salary unlocks a Solo 401(k); a cash balance plan stacks on top.
$135,500 deduction × 30%
Augusta Rule
PermanentRent your home to your business up to 14 days a year, tax-free to you.
$14,000 × 30%
Accountable plan
PermanentTax-free reimbursement for home office, phone, internet, and mileage.
About $10,000 × 30%
Deductions 1099 physicians miss
PermanentLicenses, DEA, CME, malpractice, dues, and travel between assignments.
About $18,000 × 30%
Max the family HSA
PermanentThe 2026 family HSA limit, deductible in and tax-free out.
$8,750 × 30%
Put the kids on payroll
PermanentPay your children for real work; deductible to you, near 0% to them.
$15,000 × 30%
Add a short-term rental
One-timeBuy a $750K short-term rental, run cost segregation, and the STR loophole makes the loss offset your physician income.
$750K × 85% × 30% bonus-eligible × 30%
~$25,000
Permanent savings that repeat every year: entity, Augusta, accountable plan, missed deductions, HSA, kids.
~$40,650
High-value deferral from retirement plans, taxed later, ideally at a lower rate, after decades of tax-free growth.
The $65,625 above is the recurring structure (moves 01 to 07). Add a $750K short-term rental with cost segregation (move 08) and year one jumps about $57,375 more, to roughly ~$123,000. State tax adds more on top.
- This is an illustration, not your return. Your number depends on income, specialty, state, and cash flow.
- Deferral is not magic. You pay tax on retirement dollars eventually, usually at a lower rate, after years of untaxed growth.
- Reasonable comp has to be defensible. We support the S-corp salary with a real analysis, not a guess.
- Every strategy has rules. Augusta needs a fair rate and records; the kids need real jobs; the rental needs material participation.
Illustrative example for a hypothetical physician, using 2026 federal rules. Educational, not individualized tax advice. Individual savings vary by income, specialty, state, and situation. Not all clients save this much, and results are not typical or guaranteed.
~$656,250
That is $65,625 a year, every year, for 10 years. And it is before a decade of tax-free compounding on the deferred retirement dollars. This is not a one-time win. It is a structure that pays you back every year you keep it.
~$65,625
year 1
~$328,125
5 years
~$656,250
10 years
Illustrative, based on the example above. Your number varies, and results are not typical or guaranteed.
What would your number be?
A 30-second estimate using the same 2026 methodology. Book your free 30-minute tax fit call to talk through your next steps.
Estimated year-one savings
$65,700
Illustrative estimate, 2026 federal rules, blended 30% rate. Not individualized tax advice. Your actual savings vary by specialty, cash flow, and situation. Not all clients save this much, and results are not typical or guaranteed.
One team handles all of it: S-Corp analysis, entity setup, monthly accounting, payroll, quarterly planning, proactive strategy, tax prep, and retirement coordination.+
S-Corp Analysis. Find out if an S-Corp actually saves you money, based on your income, specialty, payroll, and retirement goals, not a guess.
Entity setup, done right. Get structured correctly the first time instead of unwinding a rushed LLC later.
Monthly Accounting. Books that stay clean and decision-ready, so nothing gets reconstructed in April.
Payroll & Reasonable Comp. A defensible salary and payroll handled, so the S-Corp benefit holds up.
Quarterly Tax Planning. No underpayment penalties and no surprise April bill.
Proactive Tax Strategy. The moves that matter found before year-end, while they can still be made.
Tax Preparation. Returns filed with the strategy already built in, by the team that knows your numbers.
Retirement Coordination. Solo 401(k), backdoor and mega backdoor Roth, and employer plans, working together.
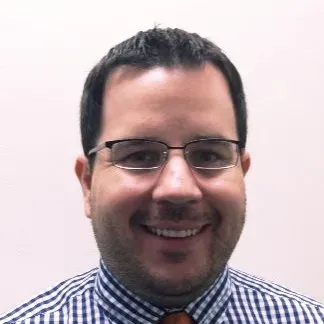
Bryan Martin, CPA, MBA
Founder of Taxstra
Taxstra works with physicians every day, across W-2, 1099, multi-state locum, and practice-owner income, so rentals, REPS, and cost segregation are familiar ground. (Bryan also holds a real estate broker's license.)
Educational, not individualized tax advice. Client scenarios are anonymized; individual results vary.
Who we work best with, and when we are not the right firm.
Best fit
- 1099 physicians earning meaningful contractor income
- Physicians considering an S-Corp
- Physicians with side income or moonlighting
- Physicians with rental real estate
- High-income W-2 physicians with large tax bills
- Dual-physician households
- Physicians who want proactive advice, not once-a-year prep
Not the right fit
- Physicians shopping only for the cheapest return
- DIY filers who just want a quick second opinion
- Anyone who will not keep clean books or follow recommendations
Questions physicians usually ask
Do all 1099 physicians need an S-Corp?+
No. The right answer depends on income, specialty, payroll requirements, compliance cost, retirement planning, and administrative burden. The point is to analyze it before assuming.
Can W-2 physicians benefit from tax planning?+
Yes, but the opportunities are different. W-2 physicians often need planning around rentals, charitable giving, retirement accounts, Backdoor Roth issues, moonlighting, equity compensation, and large tax bills.
Do you replace my current CPA?+
Taxstra can handle your strategy, tax preparation, accounting, and related planning in one place, so you are not stitching together advice from multiple providers.
Is this only for physicians with businesses?+
No. The strongest fit is often a 1099 physician, but high-income W-2 physicians with complexity can be excellent clients too.
What happens on the call?+
You talk with our onboarding team. We learn about your income, entities, and goals, may talk through your situation in general terms, and explain which services fit and what an engagement would look like, including the cost range. If it is a fit, a tailored proposal follows. We do not give advice or build your tax plan until an engagement starts, because we would not have the full picture yet.
What should I have ready?+
The booking form asks about your income types, any entities you own, your projected income, the states where you live and work, the services you want, and how you heard about us. Rough numbers are fine, and you do not need to send documents.
Sound like you? Pick a time.
A free 30-minute call with our team about your needs, how we can help, and whether we are a good fit. Tax advice, document reviews, and analysis require a paid engagement.